This will basically be a roundup. It will include signs of economic trouble brought on by Trump’s war on Iran as well as signs that dollar hegemony is under attack. That’s not a claim that the USD will somehow no longer be an important factor in world trade, but that it’s use to enforce Anglo-Zionist hegemony will be challenged. You’ll see that read in Philip Pilkington’s post, in which he speaks of structural hegemony.
Philip Pilkington @philippilk
7h
This is a strong indication that the US dollar’s structural hegemony is broken. If there is a crisis I strongly suspect there will be no “flight to safety”. Yields will rise, capital will flee - just like in any other economy.
The Kobeissi Letter @KobeissiLetter
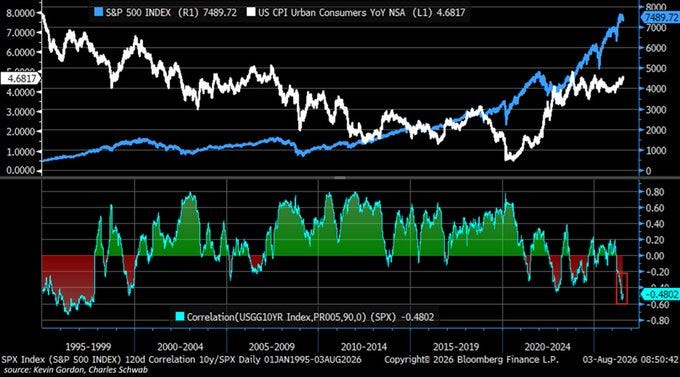
The relationship between stocks and bonds has completely flipped:
The 90-day correlation between the 10Y Treasury Yield and the S&P 500 is down to -0.48, its most negative reading since 1999.
This means that rising Treasury yields have recently been associated with weaker stock market performance, while falling yields have supported equities.
The current reading is even more negative than the 2022 bear market low of -0.42.
For context, before the 2020 pandemic, the correlation was positive for over a decade, with Treasury yields and equities often rising together as higher yields reflected stronger economic growth.
Currently, the negative correlation suggests investors are viewing higher yields less as a sign of economic strength and more as a result of inflation uncertainty and fiscal concerns.
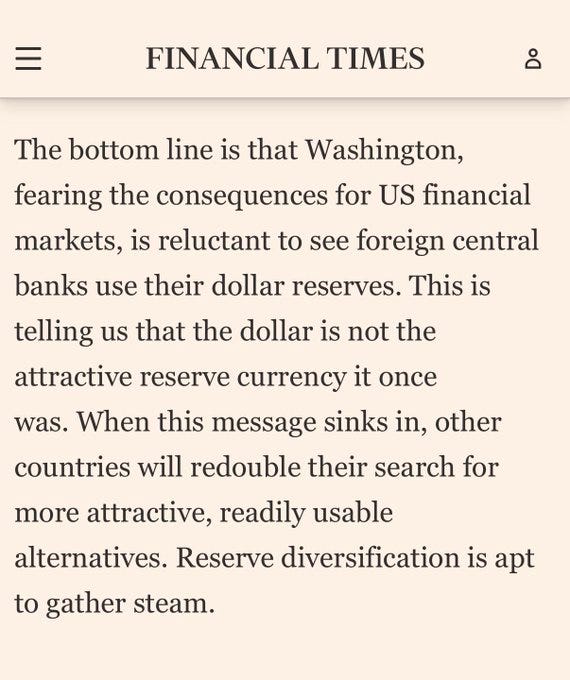
The very establishment FT is suggesting something similar. They’re looking at Bessent’s attempts to save the Yen by using Euros rather than dollars:
Luke Gromen @LukeGromen
3h
If UST reserves cannot be sold in a crisis without making said crisis worse by threatening a debt spiral, then UST’s are no longer fit for purpose as FX reserves.
In contrast, earlier this year, gold reserves were sold easily & quickly & de-escalated the crisis.
Let’s watch.
Kathleen Tyson comments—with a swipe at Bessent’s Soros past:
Kathleen Tyson @Kathleen_Tyson_
Central bank asset managers should consider trading USD reserves hampered by New York Fed veto on use for reserves in liquid dollar linked currencies. Hong Kong dollar is based on USD currency board that even Scott Bessent couldn’t destabilise - though he tried twice!
On the commodity front:
MBAeconomics @MBAeconomics1
3h
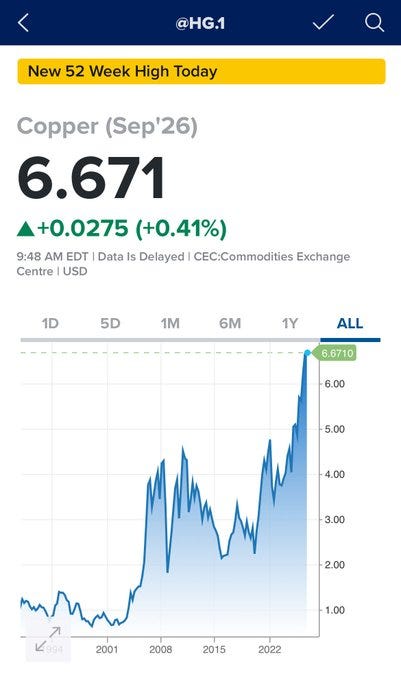
Copper casually hitting all time highs.
Hows the price of sulfuric acid doing?
The world is about to realize at the same time the value of tangible commodities!
This video features Chris Martenson talking about refined products—especially diesel:
CEO of Shell Wael Sawan has warned there is a shortage of gasoline and diesel.
Sawan in an interview with CNBC shared that since the beginning of the Iran War refineries have maximized production of jet fuel due to the fact it has tripled in price since the beginning of the conflict.
…
The Street explained the predicament shared by Sawan:
When the Iran war disrupted Middle Eastern jet fuel exports, aviation fuel prices spiked. Refineries globally, including Shell’s, responded rationally to market signals. They maximized production of the highest-priced product.
Shell increased its jet fuel production by approximately 20% in response to that price signal, according to Sawan‘s remarks.
That 20% jet fuel addition came at a direct cost. Refinery units running at maximum throughput allocate barrel inputs across competing product streams. More jet fuel output means less diesel and gasoline from the same barrel of crude.
As the jet fuel shortage eased and aviation activity normalized, the diesel and gasoline deficit that accumulated during the pivot is now showing up in product-market signals.
“The price signals are that we are short on diesel and gasoline,” Sawan said. Remember, that is a CEO with real-time visibility into global product markets telling investors and viewers that the next leg of fuel-cost pressure may arrive at the pump, not the aircraft gate.
Sal Mercogliano, maritime historian and the voice behind What is Going on With Shipping, explains why the deal may not matter.
War-risk insurance through Hormuz is running at levels the world hasn’t paid since the Tanker War, and in his words “shipping is kind of like a fainting goat”: it locks up first and asks questions later.
His warning cuts deep, because when the Houthis stopped shooting after the Gaza ceasefire, the ships never came back, and he expects the same hesitation no matter what gets signed this week.
Then it widens.
Why a single tanker run to the Black Sea now costs triple what the biggest ship on earth charges.
How China quietly refilled its reserves during the pause while Japan drained its own dry.
The real mechanism behind Beijing’s quiet win at the Panama Canal.
And the shortage he says nobody is tracking, the one that ends with gaps on American grocery shelves within a year.
The war taught every shipper on earth one lesson: the ocean is no longer safe by default.
Unlearning that will take far longer than any signing ceremony.
Thanks for reading Meaning In History! Subscribe for free to receive new posts and support my work.

That final comment, by Nawfal, reads like a U.S. House of Representatives' Impeachment Document, of POTUS.
Desperate situation: https://www.youtube.com/watch?v=lY0tRulsFHo House of El: ''America has successfully reached the financial tier of a mid20s guy who maxed out five
credit cards to buy a jet ski and is now taking out a six credit card just to pay the minimum monthly interest on the
first five. That is the backdrop. That is the economy whose Treasury Secretary just raided Europe's currency reserves
to buy 12 hours of stability in the Japanese yen market.'' Of course, it hasn't worked - his Euro raid hasn't gone unnoticed.